Pull up three different sites and search "Gretna home prices" and you'll get three different answers. Redfin shows a median sold price of $389,012 as of May 2026, up nearly 6 percent year over year. Movoto shows a median list price of $450,000 for July 2026, down 4 percent from a year earlier, with homes spending a median of 106 days on the market and running about $185 a square foot. Filter either site down to listings tagged specifically as new construction and the number moves again, closer to $475,000 across a smaller pool of homes. None of these numbers is wrong. They're measuring different slices of the same town, and the gap between them is exactly where a buyer's real decision gets made.
If you've been comparing Gretna to Elkhorn or Papillion using the median price on a listing site, you've been comparing an average of averages. The number that actually determines what you pay over the life of the loan lives one layer deeper, in a financing structure most out-of-state buyers have never heard of and most first-time buyers don't ask about until the first tax bill arrives.
Which Median Are We Even Talking About?
Here's what's actually driving the different headlines. Redfin's $389,012 is a sold price, meaning it counts only closed transactions in a single month. Movoto's $450,000 is a list price, which measures what sellers are asking rather than what buyers end up paying, and the two rarely match in a market where days on market can run past 100. Homes.com adds a third measurement entirely: a blended median sale price across new and resale homes together over the trailing twelve months, landing at $414,244, down 2 percent, with homes averaging 67 days on market against a 48-day national average.
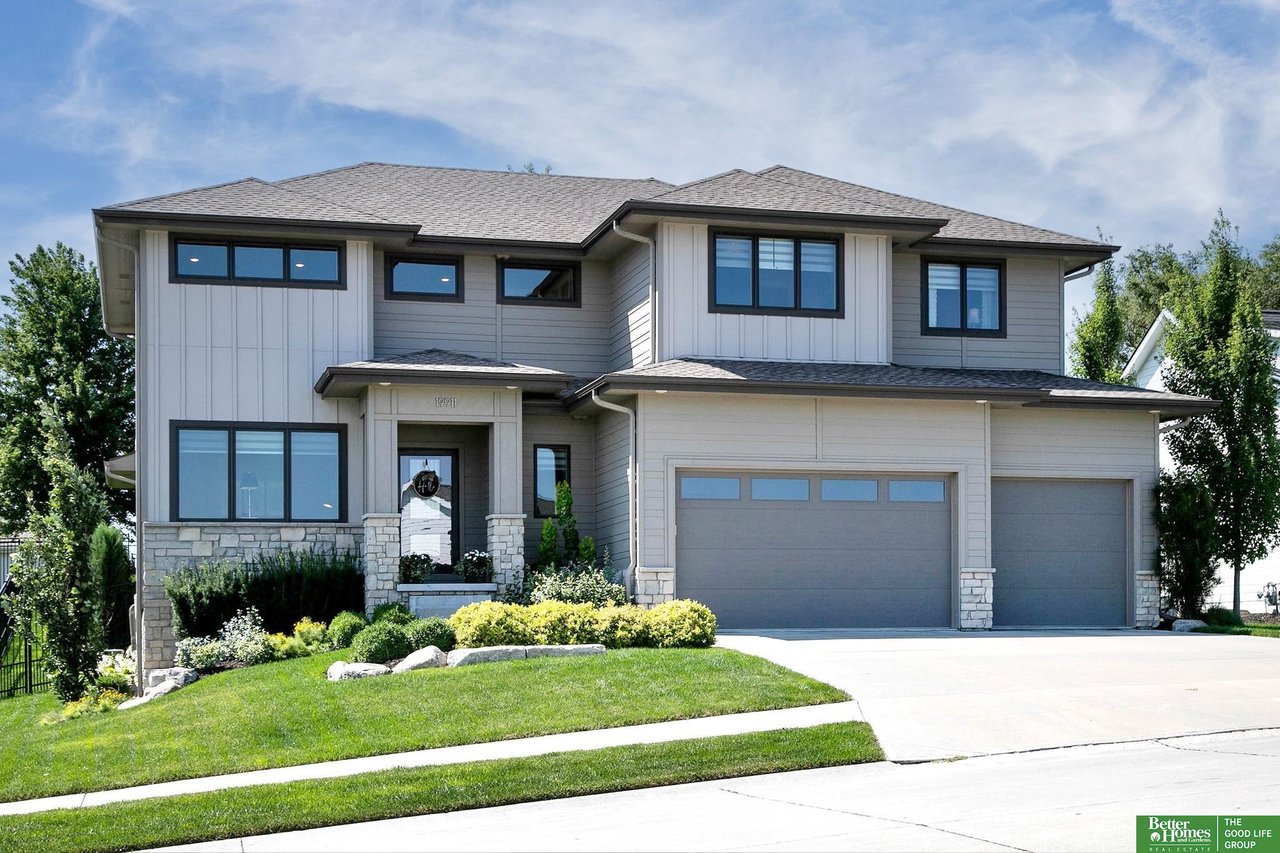
Narrow any of these searches down to homes tagged specifically new construction and the number shifts again. Redfin's new-construction filter, covering a small pool of listings, showed a median list price near $475,000. Its broader new-homes category, which pulls in more spec inventory further along in a subdivision's build-out, showed a median list price of $393,000, with homes moving in a median of 18 days.
None of these four numbers is wrong. Sold price and list price measure different things. A trailing twelve-month blend reads differently than a single month's snapshot. And new construction itself isn't one price band, it's several micro-markets bundled under one filter depending on how narrowly a site defines the term.
None of these figures tell you what a specific address will cost you to own for the next ten years. For that, you need to look past the sale price to the mechanism that built the house.
What a Sanitary and Improvement District Actually Costs You
Nebraska funds new subdivisions differently than most states. Instead of a city extending roads, sewer lines, and water mains at municipal expense, developers form a Sanitary and Improvement District, or SID, and issue bonds to cover that infrastructure themselves. Homeowners in the district then repay those bonds through an annual levy added to the property tax bill, a repayment period that typically runs 20 to 30 years.
That levy can run from a few hundred dollars a year to more than $8,000, depending on how much infrastructure the district financed and how many parcels are splitting the bond. It does not show up in the listing price. It does not show up in the square footage or the school district. It shows up the following spring, when the county assessor's notice lands in the mailbox, which for a lot of buyers is the first time they see the obligation spelled out in writing at all.
This is the actual reason a builder can advertise a lower base price on a home in a newer Gretna section than the true cost of ownership implies. The infrastructure cost hasn't disappeared. It's been moved off the sale price and onto a decade-plus tax schedule that a buyer has to ask about specifically, because it rarely gets volunteered.
In Sarpy County, where much of Gretna sits, a SID generally runs for its full bond term unless the city annexes the area first. Annexation by Gretna or Papillion can retire the levy early, which means two homes with identical floor plans a few miles apart can carry very different long-term tax pictures depending on how close each is to an annexation timeline.
Gretna Sits on a County Line, and That Matters
The SID question gets more complicated because Gretna itself straddles two counties. A parcel on the Douglas County side of town and a parcel on the Sarpy County side can carry a genuinely different effective property tax rate, even with the same ZIP code and school district on the listing sheet.
|
Douglas County portion |
Sarpy County portion |
| Median effective property tax rate |
1.87% |
1.97% |
Both figures run well above the national median effective rate of 1.02 percent, but the tenth-of-a-point gap between the two counties is the part that's easy to miss on a listing sheet. Multiply a tenth of a point against a $450,000 purchase over 20 years and it stops being a rounding error. It's also a reminder that "Gretna" on a listing sheet isn't one tax jurisdiction. Two homes with the same builder, same floor plan, and same list price can land in different counties, different school levies, and different SID repayment schedules depending on which side of an invisible line the lot sits on.
Why Builders Don't Just Lower the Price
If infrastructure costs and financing terms are doing this much work behind the scenes, a reasonable question is why builders don't just price the house lower to begin with. The answer is that the list price protects the whole subdivision's comps, not just one sale.
A builder who cuts $20,000 off the sticker price on one lot has just reset the appraised value for every unsold lot in that phase, and for every homeowner who already closed. A rate buydown or a closing cost credit accomplishes the same thing for the buyer's monthly payment without touching that number. The base price stays intact on paper. The effective cost to the buyer moves anyway, through a lower interest rate for the first year or two, or through cash applied toward closing costs.
This is the second layer of the same pattern the SID represents. The true cost of the transaction and the number printed on the listing sheet are related but not identical, and the difference between them is where the negotiation actually happens.
What This Means If You're Comparing Gretna to Resale
Across Douglas and Sarpy Counties combined, the median closed price for new construction reached $454,772 in June 2026, up 5 percent from a year earlier, while existing homes closed at a median of $328,000, up 3.8 percent over the same period. That roughly $127,000 gap is the visible half of the story. The SID levy, the county-line tax difference, and the builder incentive structure are the invisible half, and they can move the real, all-in cost of a new build closer to or further from a comparable resale depending on the specific lot.
This is why a straight median-to-median comparison between a new build in a Gretna community like Tiburon or Harvest Creek and a ten-year-old resale in an established section can mislead in either direction. The new build might carry a SID levy that adds real annual cost for another two decades. The resale might sit in a district where the SID retired years ago and that infrastructure cost simply isn't part of the tax bill anymore.
Questions to Ask Before You Write an Offer
If you're looking seriously at new construction in Gretna, in developments like Highland Pointe from Charleston Homes, Coventry Wood South from Colony Custom Homes, or a D.R. Horton floor plan like the Hamilton, a few questions will tell you more than the list price ever will:
- What is the current SID levy rate for this specific lot, and how many years remain on the bond?
- Is this parcel in Douglas County or Sarpy County, and has annexation been discussed for this district?
- Is the builder's incentive a temporary rate buydown, a permanent one, or a closing cost credit, and what does the payment look like once any temporary buydown expires?
- What is the total effective tax rate once the SID levy is added to the base county and school district rate?
A builder who answers these clearly and in writing before you sign is telling you something about how they do business. A builder who waves the question off is telling you something too.
Frequently Asked Questions
Does every new home in Gretna have a SID levy?
Not automatically, but the majority of newer subdivisions built outside existing city infrastructure do. Established, already-annexed neighborhoods may have no active levy at all, which is worth confirming before comparing tax pictures across two listings.
Does the SID levy ever go away?
Yes. It runs until the bond is retired, typically 20 to 30 years, or until the city annexes the district, whichever comes first. Annexation status is public record and worth asking about directly.
Why do different websites show such different Gretna prices?
Because they're measuring different pools of homes. A site filtering strictly for "new construction" tags will show a different median than one showing all "new homes," and both differ from a blended median across new and resale together. None is incorrect. They're answering different questions.
If you're weighing a new build against a resale in Gretna, or trying to figure out what a specific lot's tax picture actually looks like five years out, that's exactly the kind of homework Stacey Reid and the team do before a client ever writes an offer. Schedule a Consultation and get the real numbers for the address you're actually considering, not just the median on the listing page.